My most recent Corporate Law Jotwell post, Bots as Corporate Directors? An Exploration of AI in Corporate Governance, promotes Zhaoyi Li’s Artificial Fiduciaries, published in 81 Wash. & Lee L. Rev. 1299 (2024). In her article, Li posits, develops, and interrogates the use of AI agents as coprorate directors. This may seem like a totally wild idea to many, including this blogger. Having said that, just as I was completing my jot, Delaware announced its proposal for a new legal business entity, the Artificial Intelligence Company (AIC), which would be managed by artificial–rather than human–intelligence. I was able to add brief references to that proposal into the jot at the last minute, thanks to the patient Jotwell editors. After reading Li’s article and learning a bit about the Delaware proposal, the idea of corporate governance through artificial intelligence has taken on new meaning and importance for me.

You can find my jot here. I recommend Li’s article, even if the idea of AI agents as corporate directors is not yet ready for prime time, as Li readily admits. I conclude the jot by noting that “Li’s arguments and reflections offer an opportunity to explore how the advent and ongoing development of AI may impact—is already impacting—group decision making in corporations and other organizations that have collective decision making as a central management feature.” Published reports like this one unsurprisingly note a realtively widespread use of artificial intelligence by corporate direcors (even if only for a narrow band of tasks).

Read Li’s article. Her visioning and analysis offer much food for thought. As both a business law prof and a director of a financial services firm, it made me think . . . .
Duquesne University, Pittsburgh, PA
Oct 30, 2026
Position Number: 350035

The Thomas R. Kline School of Law of Duquesne University, located in Pittsburgh, Pennsylvania, invites applications from entry-level and lateral candidates for the full-time tenured/tenure-track faculty position to begin the 2027-2028 academic year.

We welcome applications from candidates across all areas of legal scholarship and teaching. Curricular needs include Civil Procedure, Torts, and Contracts. Additional areas of interest include Health Law and Legal Research and Writing. Candidates must be available to teach primarily in person, though some courses may be offered in online, hybrid, or HyFlex formats.

Qualifications

Juris Doctor from an ABA-accredited law school.

Strong academic credentials and demonstrated potential for excellence in teaching, scholarship, and service.

Alternatively, the applicants may possess any equivalent combination of experience and training, which provides the knowledge, skills, and abilities required to perform the essential job functions.

Ability to establish and maintain effective working relationships with the University Community.

Ability and willingness to contribute actively to the Mission of the University and to respect the Spiritan Catholic identity of Duquesne University. The Mission is implemented through a commitment to academic excellence, a spirit of service, moral and spiritual values, sensitivity to world concerns, and an ecumenical campus community.

Application Instructions

Applicants are asked to submit a cover letter/letter of intent, resume/CV, and contact information for a minimum of three professional references.

The letter of intent should include comments on ability to teach in flexible environments.

Application review will begin immediately and will continue until the position is filled.

Applicants with questions about the position may contact the chair of the Faculty Recruitment Committee, Professor Ann Schiavone, at 412-396-2117 or schiavonea@duq.edu.

The application can be reached here: https://apply.interfolio.com/196717

In an earlier post, I flagged the launch of a pilot program for the Nevada Business Court. Recent significant decisions can now be found on the pilot program’s webpage, making the application 0f Nevada law more readily observable. There are now three decisions available, all drafted by Judge Gall. Many thanks to Boyd Law Student Amanda Vaskov for reviewing the decisions and drafting short summaries. I’ve placed the summaries after the jump below.

The three cases involve different issues. Passley v. Ameritek Ventures shows a plaintiff successfully rebutting Nevada’s statutory business judgment rule and the Court voiding transactions. David Corbett v. Gary Rhea Ins. Agency features the Court denying a motion for a preliminary injunction to preserve records and assets because the parties were already under a preservation obligation and the plaintiff made no showing that there was any imminent risk of asset dissipation. In Hanchil Kim and Hyunju Lee v. Yoon-Sik Kim and Olden Star, Inc., the Court dismissed a suit for lack of personal jurisdiction after “Plaintiffs’ counsel conceded that there are no derivative claims in the first amended complaint, and that the entirety of Plaintiffs’ claims” were against a defendant directly.

I was surprised by the outcome in Olden Star because it involved some claims that defendants “deprived Plaintiffs of their Nevada-law stockholder rights under NRS Chapter 78[.]”

So I looked a bit deeper. Sometimes cases come out in surprising ways because of how the parties argue them and because courts let them argue their own cases under party presentation principles. The decision makes sense given what the parties presented to the Court. The plaintiff has the burden to establish personal jurisdiction. After the defendant moved to dismiss for lack of personal jurisdiction, the Plaintiffs’ opposition never cited NRS 75.160, which I read to mean that the directors of Nevada corporations consent to claims involving duties owed on account of their director position. Like Delaware, Nevada has a director consent statute. It provides that:

1.  Every nonresident of this State who, on or after October 1, 2013, accepts election or appointment, including reelection or reappointment, as a management person of an entity, or who, on or after October 1, 2014, serves in such capacity, and every resident of this State who accepts election or appointment or serves in such capacity and thereafter removes residence from this State shall be deemed, by the acceptance or by the service, to have consented to the appointment of the registered agent of the entity as an agent upon whom service of process may be made in all civil actions or proceedings brought in this State by, on behalf of or against the entity in which the management person is a necessary or proper party, or in any action or proceeding against the management person for a violation of a duty in such capacity, whether or not the person continues to serve as the management person at the time the action or proceeding is commenced. The acceptance or the service by the management person shall be deemed to be signification of the consent of the management person that any process so served has the same legal force and validity as if served upon the management person within this State.

The parties didn’t raise the statute and the Court didn’t discuss it. The case was not litigated by lawyers specializing in corporate law. The parties built their argument around Consipio Holding, BV v. Carlberg, 128 Nev. 454, 459 (2012) which followed the U.S. Supreme Court’s decision in Shaffer v. Heitner, 433 U.S. 186 (1977) . Nevada’s consent statute was passed in 2013. As the plaintiffs didn’t argue that the defendants consented to the jurisdiction in Nevada under the statute, I wouldn’t read Olden Star as indicating that plaintiffs cannot establish personal jurisdiction over the directors of Nevada corporations for similar claims.

Succinct Case summaries

California passed a pair of climate change reporting laws, applicable to companies that do a certain amount of business in the state.

The first required disclosure of Scope 1, 2, and 3 emissions; the second required reporting in line with the Task Force on Climate-Related Financial Disclosures (TCFD) framework, which includes disclosures about physical risk and transition risk from climate change, as well as the process for identifying and managing those risks.

California justified the laws, in part, on the grounds that they were necessary to “provide investors with information relevant to capital markets,” and businesses sued to enjoin the laws, arguing that the disclosures violate the First Amendment.

This week, the Ninth Circuit agreed that the Scope 3 disclosures, and the TCFD disclosure requirements – but not the Scope 1 and 2 disclosure requirements – constituted impermissible compelled speech.  And though California did say that the disclosures were necessary for other purposes, most of the analysis turned on disclosure to investors (and the court pointed out that 75% of the businesses subject to the law are publicly traded).

The gist of the majority opinion is that Scope 1 and 2 disclosures are sufficiently tied to the firm and its economic value to constitute commercial speech, subject to intermediate scrutiny, but the Scope 3 and TCFD disclosures are not commercial speech, and therefore disclosure requirements are subject to strict scrutiny.

Okay, so my first question – and it actually is one – is whether the entire law is, or should be, deemed preempted by the National Securities Markets Improvement Act, which says states shall not “directly or indirectly prohibit, limit, or impose any conditions upon the use of … any offering document that is prepared by or on behalf of the issuer; or any proxy statement, report to shareholders, or other disclosure document … that is required to be and is filed with the Commission…” with respect to publicly traded securities.

But more generally, I’m kind of amazed that only Judge Bennett in concurrence/dissent even engaged the question of how the Ninth Circuit’s ruling interacts with the securities laws.

The Ninth Circuit held that Scope 3 determinations “compel[] companies to collect, synthesize, and report information about the conduct of independent actors across complex commercial networks, including suppliers, customers, distributors, and other third parties throughout the value chain.  Because Scope 3 disclosures concern diffuse third-party conduct in the value chain, they are insufficiently tethered to the reporting entity’s own operations and capital transactions to qualify as commercial speech.”

From there, the court determined – essentially categorically – that they are too inherently uncertain to be of much use to investors.

As for the TCFD disclosures, the court concluded they were “noncommercial speech” that include “subjective ideological assessments,” such as identifying the transitional and physical risks of climate change, and the process for identifying and managing these risks.  The court explained, “SB 261 requires companies to opine on whether climate change poses financial risks to their operations and business model, thereby making predictive judgments about uncertain future conditions. Companies must also analyze and disclose whether mitigating those risks is worth the cost, requiring them to make normative assessments about competing priorities and values….SB 261 ‘would require [a covered entity] to convey the company’s policy views on intensely debated and politically fraught topics….’” Thus, they were not commercial speech.

Reader, my jaw dropped.

The securities laws today require companies to make numerous assessments about the risks and their mitigation efforts (check out disclosures required about cybersecurity). I can’t even imagine what the world would look like if regulators had to make fine-tuned judgments about whether a required disclosure concerned “diffuse third-party conduct,” let alone “subjective ideological assessments” of risk. Is the Ninth Circuit saying all risk-related securities disclosures are unconstitutional?  Or is it just because climate change itself is politicized?  The Ninth Circuit accepts that climate change is in fact a real thing with real economic effects on business, so if you that’s baseline, does the mere fact that some people continue to dispute the reality of climate change turn it into a politicized topic on which the government cannot compel speech to investors?

The concurrence/dissent by Judge Bennett is even more baffling.  Though he has a drive-by reference to the securities laws – which he views as subject to lesser scrutiny solely because they prevent fraud – he ultimately concludes that for any speech to count as “commercial” (and therefore subject to lesser scrutiny), it must be about a product or service being offered for sale.  And though he agreed that sales of “stock” count, he concluded all of the required disclosures were noncommercial because:

As to debt, SB 253’s emissions data informs market participants about the issuer or purchaser of debt, not the debt “product” itself. The same is true of insurance. SB 253’s disclosures inform market participants about the insurer or the insured, not the insurance product offered for sale. 

The analysis does not differ as to stock, in my view…. From this definition, it follows that core information about stock as a “product” concerns a stockholder’s rights to (1) control management (most prominently, through voting); (2) claim an interest in the corporation’s assets upon liquidation; and (3) to claim a share of the corporation’s residual earnings….

But because firm-level disclosures convey information about the issuer of stock, such disclosures refer only indirectly—through the information recipient’s own analysis and inference—to the price of stock, and thus to the specific “product” at issue…. Put more directly, the mere fact that investors value stock based on information about the issuing corporation cannot “mean that basically any compelled disclosure by any business about its activities” is commercial in nature….

I would require government to show that the compelled disclosure informs investors about stock itself. In my view, such a close tether is missing when government compels the disclosure of information about, more broadly, companies that issue stock….

SB 261 also compels noncommercial speech. A covered entity’s governance, strategy, risk management, and internal metrics and targets relating to climate change inform the listener about the company, not the company’s stock.

Excuse me?  Information about the issuer of stock is not information about the stock?  If so, we have to rethink the Securities Act of 1933. 

Which, it should go without saying, requires disclosure of far more information than necessary merely to prevent fraud; it requires extensive disclosures of risk – Anthropic has about 94 pages on it – so that investors can gauge the value of the company and thus the value of an investment.

Hey, artificial intelligence superintelligence is politically charged; was it unconstitutional to require Anthropic to warn about the catastrophic risks to humanity?

Anyway, that’s really all I’ve got except that as soon as Chair Atkins gets hold of this opinion, I assume it will assist in his project of dismantling all securities regulation.

Lagniappe.  And while we’re on the subject of the intersection of corporate and securities law with the First Amendment, it’s worth checking out the New York Times’s brief opposing an inspection demand issued by Florida’s state pension system and the National Center for Public Policy Research.  Ostensibly as “shareholders,” they demanded internal books and records in response to a Nicholas Kristof column accusing Israelis of raping Palestinians.  In addition to pointing out that their purposes are transparently political rather than investment-oriented, the NYT argues that because the Florida pension system is a state entity, the demand itself violates the First Amendment.

Edit: George Georgiev points out that Exxon did make an argument for NSMIA preemption of California’s laws in a parallel case, and the argument was rejected earlier this year. See Exxon Mobil v. Sanchez, 2026 WL 2323111 (E.D. Cal. Aug. 11, 2026). He also submitted an expert report to the district court in the US Chamber case.

And another thing. New Shareholder Primacy podcast is up!  This week, me and Mike Levin talk about the election’s effect on corporate law and DExit, and about Delaware’s new draft legislation regarding shareholder proposals. Here at Apple; here at Spotify; and here at YouTube.

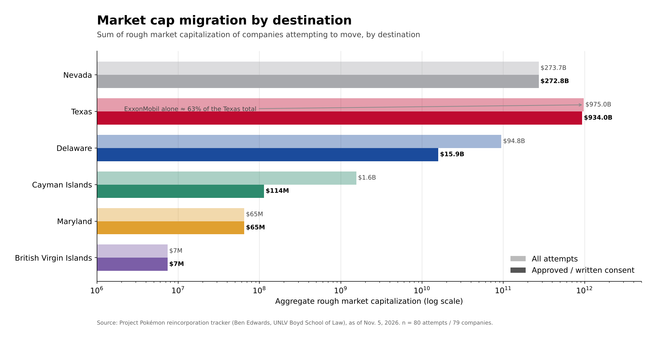
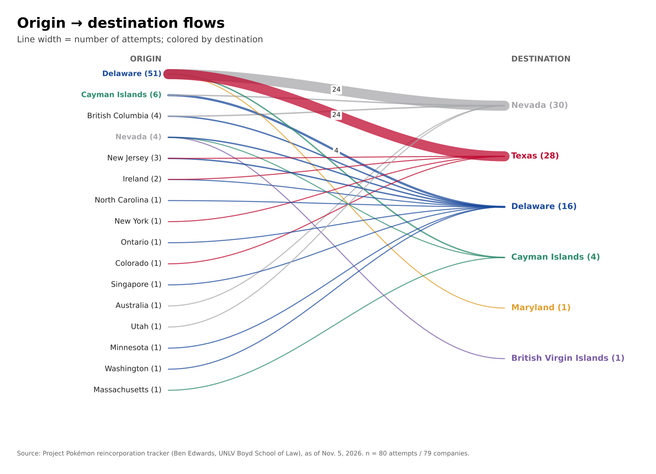
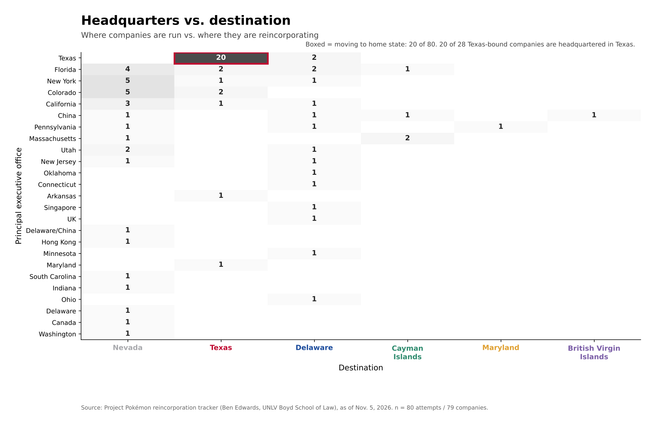
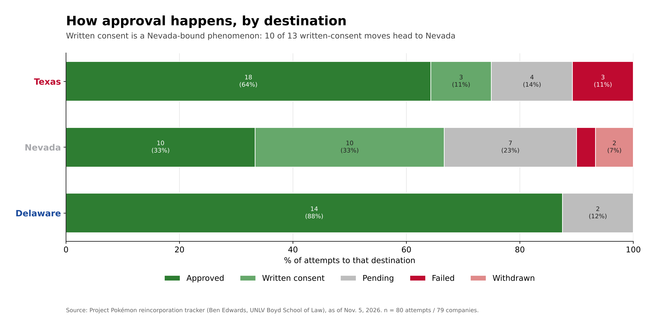
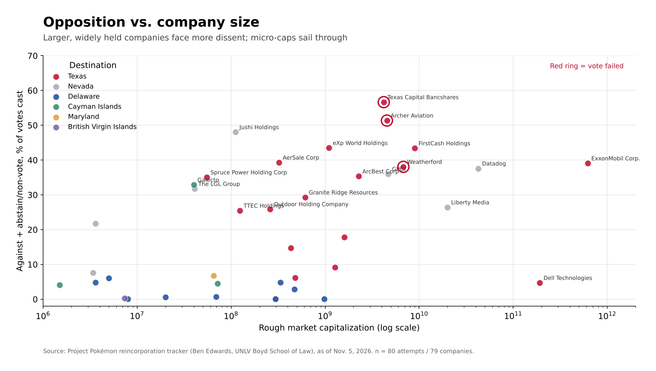
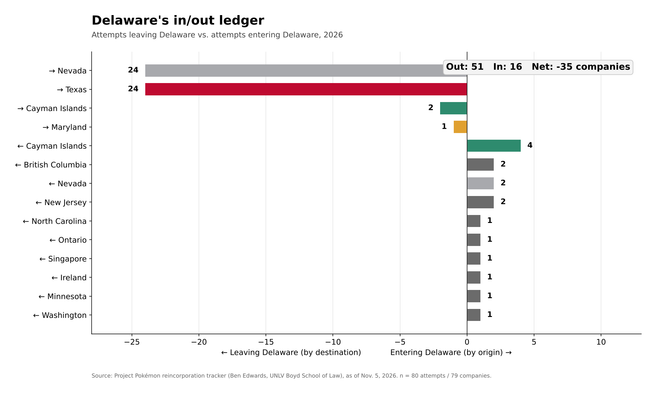
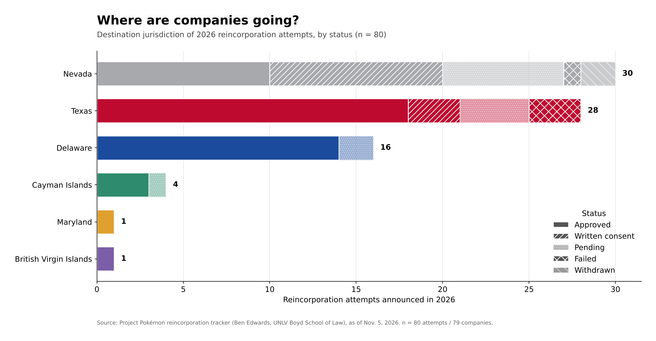
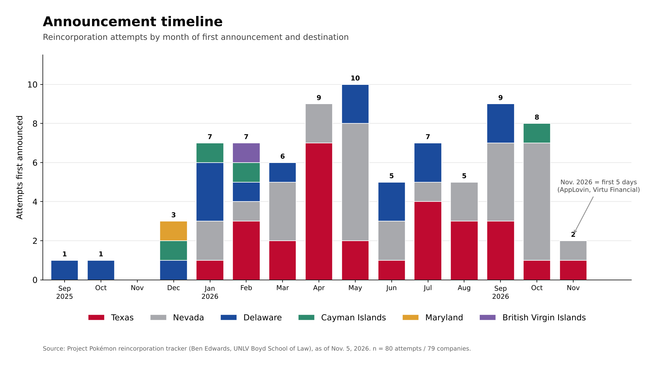
Moves have continued. There were 71 in mid-October. Now, the number stands at 80. As always, a copy of our spreadsheet is available here. As usual, I’ve had Claude generate infographics to help visualize the movement. The full list is after the jump below.

Nevada Takes Lead In Companies

Nevada recently displaced Texas as the leading destination, drawing 30 companies to Texas’s 28. Delaware’s count also grew by one as I found a de-SPAC that I hadn’t previously tracked.

Movement Over Time

Movement this year has not been limited to proxy season. It’s hard to know how much more we’ll see in November, but we’ve got two in the first week.

Rough Equity Value

Texas continues to lead on overall rough market capitalization. This particular chart uses a log scale, so the gap looks smaller than it really is.

Migration Patterns

Both Delaware and Texas draw from a fairly wide range of states. Nevada has some other jurisdictions in the mix, but has primarily drawn from Delaware.

Headquarters

Texas continues to do very well with companies headquartered there.

Approval Methods

Nevada has largely picked up moves approved by written consent, while Texas and Delaware moves more often go to a shareholder vote.

Company Size and Vote Patterns

This chart is new. Larger, more widely held companies have faced more opposition. Smaller firms have largely not had trouble. But many of the smallest moves were also to Delaware.

Delaware’s Ledger

If you’re tracking Delaware specifically, exits largely go to Nevada or Texas, but Delaware remains a preferred destination for international moves.

As always, special thanks to Boyd Law students Hunter Hawkins, Enya Dinca, and Rocco Marino for their help maintaining and updating the spreadsheet.

Continue Reading Early November 2026 Reincorporation Update

So, the Democrats swept Texas. The headline news is the Senate race, but from a corporate perspective, the bigger deal is a Democratic governor, Lieutenant governor, Attorney General, state house, and potentially as of this writing significant moves toward Democrats on the Texas Supreme Court and the Texas 15th Circuit Court of Appeals.

The new Texas business courts have judges that are appointed by the governor for 2-year terms, which makes them accountable to the political branches, and those politics just shifted. Additionally, appeals from the business courts are heard by the 15th Circuit Court of Appeals. Point being, Texas statutory law is still what it is, but to the extent there are open questions of interpretation, the political shift may turn out to be consequential.

Plus, of course, Texas has been at the forefront of the war on ESG. In addition to passing a proxy advisor law that specifically burdens ESG advice, Texas’s current attorney general, Ken Paxton, has sued both ISS and Glass Lewis, alleging they deceive their clients with politically biased recommendations. He has also taken the lead in a lawsuit alleging BlackRock and State Street violated antitrust laws, and deceived consumers, by pushing to reduce coal output.

We may see a lot of that action halted. The new Democratic attorney general may not have the same appetite to pursue these lawsuits, and he may not even be all that vigorous about defending the proxy advisor law, which is currently on hold due to a judge’s conclusion that it violates the First Amendment.

But the biggest effects may be felt in Delaware. To the extent Texas has posed a threat to Delaware’s dominance, a Blue Texas may not seem as attractive to corporate boards looking for an escape hatch. And that may relieve some of the pressure on Delaware (and its judiciary) to accommodate board demands.

Edit: And I’ll elaborate (since I threw this post up pretty quickly) – the difference between a Blue Texas and a Blue Delaware is that Delaware has made every effort to keep partisan politics out of its corporate law; Texas, however, did the other thing. And now we know that its partisan direction is not stable.

We can go further; it’s frequently been observed that the real threat to Delaware comes from the potential for federal preemption. If federal preemption is on the table, Delaware has an incentive to demand more from corporate boards, and corporate boards have an incentive not to try to evade that discipline by escaping to other states. The last few years made it seem like preemption was simply not an option, which gave managerial threats to leave the state more credibility, and that much may have changed last night.

But the most important implications, of course are for academia. Everyone’s taken up writing about state capitalism (including me, in draft), and now what are we supposed to do? I for one have some changes to make to this paper, I guess (sorry, student editors).

And another thing. New Shareholder Primacy podcast is up! This week, me and Mike Levin talk to Lauren Pringle, EIC of the Chancery Daily. Here at Spotify; here at Apple; and here at Youtube.

Here is ISS’s press release on it; here is a Law360 article on a recent hearing.

The gist is, in the guise of investigating whether ISS is complying with its obligations as an investment adviser, the SEC is seeking a complete list of client voting records and the advice ISS communicated to clients.

It’s not hard to see what this is about; the SEC is trying to determine which clients are advocating for ESG matters, which can include racial diversity proposals, climate change issues, and even, not long, ago, abortion rights. The next step is for the SEC or perhaps another agency (Labor) to investigate whether the institutional client is complying with its own fiduciary obligations, with matters that lean left singled out for special scrutiny as presumptively not wealth maximizing. Ultimately, though, the goal is to use the fiduciary duties of institutions as a kind of cudgel to dictate their voting behavior. As I previously wrote:

in some ways, this is about Trump admin bugaboos like diversity and climate change, but in others, the Trump Admin and state regulators are pretty explicit about stamping out all challenges to management (see below on Indiana’s law). And if regulators have the freedom to decide (on a theory of what counts as wealth maximization) which boards can be challenged by shareholders and which cannot, that leaves corporate management awfully … dependent … on the state to maintain their positions, with all the implications that follow.

The critical thing here is that the administration doesn’t actually have to sue anyone for violating their duties; all it has to do is impose excess paperwork on any voting decisions that don’t meet the administration’s presumptive views of what is “wealth maximizing,” which necessarily excludes anything that doesn’t align with the administration’s politics.

Bright side? I guess if every company goes dual class, we don’t have to care much about shareholder voting anymore.

And another thing. New Shareholder Primacy podcast is up! This week, me and Mike Levin talk about the recapitalization at Meta (now the subject of a shiny new shareholder lawsuit, which was publicized just an hour or so before we recorded), and the advance notice bylaw decision at Empery. Here at Apple; here at Spotify; and here at YouTube.

In my first post today, I wrote about VC Laster’s opinion in In re Cloudflare Stockholder Litigation and its implications for future similar transactions.

Now I turn to a separate question: How should DGCL 144’s safe harbor be applied to conflicted controller deals?

Here, I have to say, I disagree with VC Laster’s interpretation of the text of the statute – and I’m more in line with Professor Steve Bainbridge’s view but I don’t completely agree with him either.  We shall call this, “certainty.”

Anyway, this is going to be a long and extremely technical reading of DGCL 144, for the nerds who like that sort of thing.  You have been warned. 

Continue Reading Cloudflare: The Statutory Interpretation Post

Last week, VC Laster issued a decision in In re Cloudflare Stockholder Litigation. I previously blogged about this case twice. In brief: Cloudflare is a controlled company due to its dual class stock, but that meant its founders couldn’t sell stock and also maintain control.  To rectify this problem, they prevailed upon the board to propose a charter amendment that would recapitalize the company in a manner that (1) did not run afoul of Nasdaq listing rules, and (2) would allow them to both maintain their high-vote shares while selling down their economic stake.

Once upon a time, this kind of conflicted deal could only have been cleansed in Delaware by approval of an independent committee and disinterested shareholders.  Before that, it could not have been cleansed at all – it would be subject to entire fairness review.

But post-SB21, all controller conflicts other than take-privates can be cleansed by independent committee, and that’s what our founders were banking on.

But!  Shareholders who filed suit to challenge the arrangement argued that SB21’s new cleansing procedures did not apply, because this transaction fell into a carveout, providing that the cleansing regime would not “limit judicial review for purposes of injunctive relief of provisions or devices designed or intended to deter, delay, or preclude a change of control or other transaction involving the corporation or a change in the composition of the board of directors.”

Precisely because there was a plausible argument that this deal could not be cleansed by independent committee, the defendants agreed to expedited proceedings and discovery.  Which uncovered numerous aspects of the committee process that called into question the committee’s good faith.  Notably, even if SB 21 applies, lack of good faith on the part of the independent special committee is grounds to conclude a conflict transaction is not cleansed, and therefore subject to entire fairness review.

Which led to VC Laster’s ruling last week.

The headline is, he rejected the plaintiffs’ argument that recapitalizations of this sort do not get the benefit of SB 21’s cleansing procedures – rather, looking to the statutory history, he concluded this was precisely the kind of transaction SB 21 was intended to cover.

I can’t say I blame him; the plaintiffs’ argument would, uncomfortably, mean that if a plaintiff sues for equitable relief before a transaction is completed, the cleansing required would be more onerous than if a plaintiff sues for damages after a transaction is completed, and that’s just weird.

But, now that VC Laster had evidence before him about how the special committee actually functioned, he concluded that there was a reasonable probability that it failed to act in good faith, as DGCL 144’s cleansing regime requires, and he preliminarily enjoined the recapitalization.

Now, I don’t take issue with his headline ruling, but I do disagree with aspects of how he interpreted the statute.  I’m going to do a separate post on that, for the nerds who really want to do a close read of DGCL 144’s language, because it gets very very long. Update: Here is that post.

But here’s the thing.  VC Laster’s ruling came down on Friday, October 16.  Just one business day later – on Monday, October 19 – Meta’s board voted to recapitalize the company to create a new class of voting shares, that would allow Mark Zuckerberg to cash out some of his existing stake without diminishing his voting control.

The SEC filing has a whole song and dance about how California’s impending wealth tax was going to force him to move to avoid selling his shares to pay the bill, and so the board “bargained” to keep in in California – or wherever the company’s headquarters are – by creating nonvoting stock.

And let’s just say, because we now know that DGCL 144’s safe harbors do apply to these kinds of transactions, future plaintiffs will not get discovery into how they are negotiated. Revised Section 220 will not, in most instances, allow plaintiffs to get access to informal board materials – only the heavily lawyered formal ones which will, no doubt, detail a pristine process. 

Which means plaintiffs will not be able to test the Meta board’s assertion that it was necessary to recapitalize the company to keep Zuckerberg from leaving California – before the tax bill actually passes, before it survives legal challenges, before testing alternatives like allowing him to pledge more of his stock, or pulling a Brian Niccol. (I note that the SEC filing states the board proposed creating the nonvoting stock conditional on the tax bill actually going into effect, but then Zuckerberg said, “Wait, what if another jurisdiction passes a wealth tax? Didn’t think of that, did you?” and the committee agreed).

On this, let us all remember that 10 years ago, Meta – then Facebook – pulled the exact same stunt.  Zuckerberg wanted to create a class of nonvoting stock so that he could sell shares while retaining control; a special committee was formed to “negotiate” with him.  But that was before SB 21, and conflict transactions with controllers required both independent committee approval and disinterested shareholder approval to avoid entire fairness review and thus trial.  Facebook’s disinterested shareholders overwhelmingly rejected the recapitalization, and plaintiffs challenging the deal were able to get discovery on their way to trial – only to learn how verkakte the committee process was, and the whole idea was dropped.

This time, though, we’re expected to believe it’s all about California’s wealth tax, just at the precise moment the board can be reasonably confident shareholders will not be able to inquire about their deliberations past formal board materials.

And another thing. New Shareholder Primacy podcast is up!  This week, me and Mike Levin talk about retail voting programs. Here at Apple; here at Spotify; and here at YouTube.

June 6–11, 2027 | Lexington, Virginia

Washington and Lee University School of Law (“W&L Law”) invites up to ten tenure-track or tenured legal scholars to join its faculty for an intensive writing retreat at House Mountain Inn in Virginia’s scenic Shenandoah Valley, a region long home to artists, artisans, and scholars alike.

Nestled high atop the slopes of Big House Mountain, House Mountain Inn offers 1,000 private acres of mountain preserve with sweeping views of the surrounding landscape. This peaceful setting provides an opportunity for scholars to step away from the demands of everday life and devote sustained attention to their research and writing.

The Retreat is designed to balance independent writing time with opportunities for thoughtful intellectual exchange and informal conversation among colleagues. We convene a small group of scholars, working across different fields and methodological traditions, with the hope of fostering an environment that encourages new ideas and lasting professional relationships.

The Retreat reflects W&L Law’s longstanding commitment to advancing legal scholarship and cultivating a vibrant intellectual community grounded in curiosity, collaboration, and collegiality.

The 2027 Writing Retreat will take place from Sunday, June 6, through Friday, June 11, 2027. Participants are expected to attend for the full duration of the retreat to support a shared, immersive writing experience.

FUNDING

W&L Law will provide lodging and meals for all participants at House Mountain Inn, together with a travel stipend of up to $500. Additional travel assistance may be available based on individual financial need.

Funding for the retreat is generously provided by W&L Law’s Frances Lewis Law Center, an independently endowed institute dedicated to enriching the intellectual life of the law school community and supporting legal scholarship and academic exchange.

SUBMISSION GUIDELINES

All tenure-track and tenured faculty at U.S. law schools are eligible to apply, provided their proposed research projects fall within the retreat’s scholarly focus.

The 2027 Writing Retreat will focus exclusively on public-law scholarship, meaning works related to government oversight, enforcement, administration, liability, and separation of powers. We welcome public-law scholarship within an array of fields, including:

  • Administrative law
  • Antidiscrimination law and theory
  • Civil rights
  • Constitutional law
  • Consumer protection
  • Criminal law
  • Critical legal studies
  • Cyber law
  • Election law
  • Environmental law
  • Evidence
  • Family law
  • Federal courts
  • Health law
  • Immigration
  • Information technology law
  • Jurisprudence
  • Labor law
  • Legislation and statutory interpretation
  • Public international law

We encourage submissions that approach these subjects from a variety of theoretical, doctrinal, empirical, comparative, and interdisciplinary perspectives.

Applicants should submit a curriculum vitae and a research proposal of no more than 1,500 words describing the project they intend to develop during the retreat. Proposals should identify the project’s central topic, research methodology, stage of development, potential contribution to scholarship and practice, and relationship to one or more of the public-law fields identified above.

Application materials should be submitted as PDFs by email to:

Kish Parella — parellak@wlu.edu
Alison Rogers — arogers@wlu.edu

Please use the subject line “2027 W&L Law Writing Retreat.”

Application Deadline: February 1, 2027

Submissions will be reviewed by a committee of W&L Law faculty. Selection will be based on the proposed project’s scholarly promise, its alignment with the retreat’s public-law focus, and its contribution to a diverse range of topics, perspectives, and methodologies.

ABOUT W&L LAW

Founded in 1749, Washington and Lee University is one of the nation’s oldest institutions of higher learning, and its School of Law reflects that enduring academic tradition. W&L Law fosters a collaborative environment in which scholarly inquiry thrives, enabling faculty to engage deeply with complex legal questions while maintaining a collegial and supportive academic culture.

Located in Virginia’s historic Shenandoah Valley, the Law School offers a setting that is both intellectually stimulating and uniquely conducive to focused scholarly work.

We look forward to welcoming colleagues to the Blue Mountain Writing Retreat for a week of productive writing, thoughtful conversation, and scholarly community building.