Is, I believe, proposing to vote all uninstructed shares to mirror vote with the voting shares? Which I believe means that in situations that require a majority of all outstanding shares to vote in favor – mergers, charter amendments, and the like – nonvotes would no longer be “no” votes, and a majority of voting shares would be able to swing it.
2026 – Midyear IPO Trends
With the discussion over reincorporating companies continuing, the other place to watch to observe jurisdictional trends is the IPO market. I recently covered Delaware’s recent report that it pulled in “nearly 70%” of IPOs last year. But what does 2026 look like so far?
Answering that question requires gathering a lot of information. But we now have some spreadsheets thanks to some student help. I’m enormously grateful to two student research assistants, Boyd Law student Rocco Marino and UNLV Honors College undergraduate student Micaela Benavidez-Sosa, for all the work they did to pull together this information. This remains a work in progress and we’re continuing to refine the spreadsheets. If you see ways to make them more useful, please email me and I’ll take a look.
We aimed to gather information about all of the IPOs or direct listings occurring in the first half of 2026. A full copy of our spreadsheet is available here. I used Claude to create the infographics. Any errors in this analysis are mine alone.
Return of the SPAC
First, some insights. SPACS are back! This has been reported elsewhere, but many of the IPOs we tracked were SPACs. Overwhelmingly, these went to the Caymans. To understand trends, I’m breaking our infographics down into with and without SPACs because operating company IPOs are different and probably a better signal as to what’s happening.
SPAC IPOs vs Operating Co. IPOs.
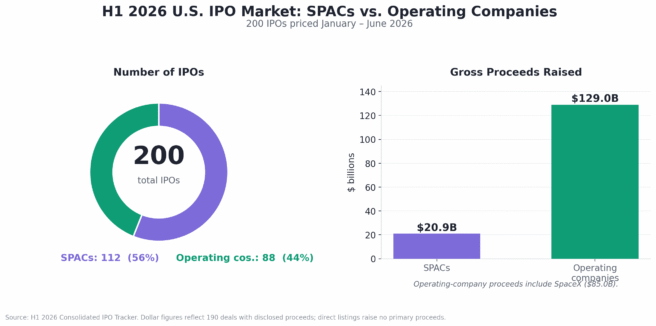
On the SPAC front, almost all of the SPAC IPOs were in the Caymans. One went to Delaware.
All IPOs By Jurisdiction & Capital Raised
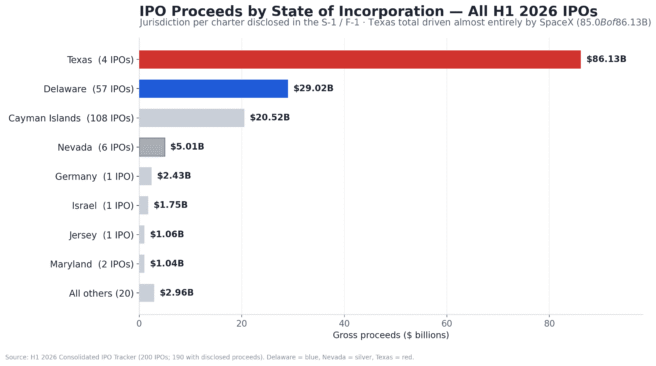
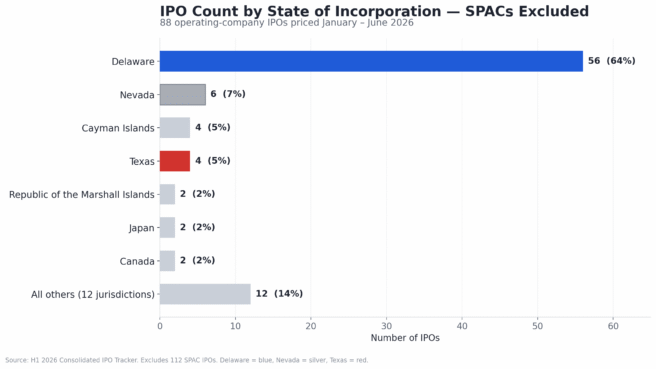
When you exclude SPACs from the mix, it shows a different percentage.
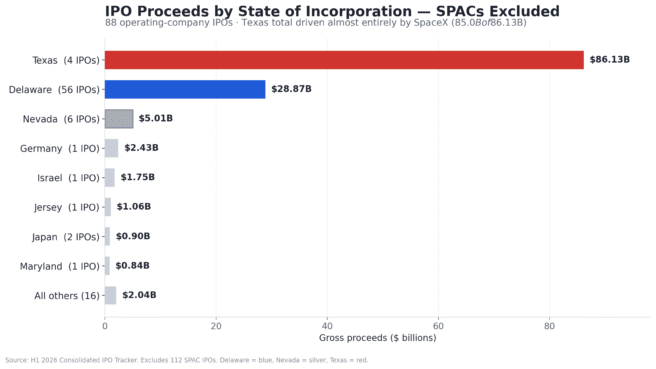
The Caymans just vanish off the chart. It’s nearly all SPACs there.
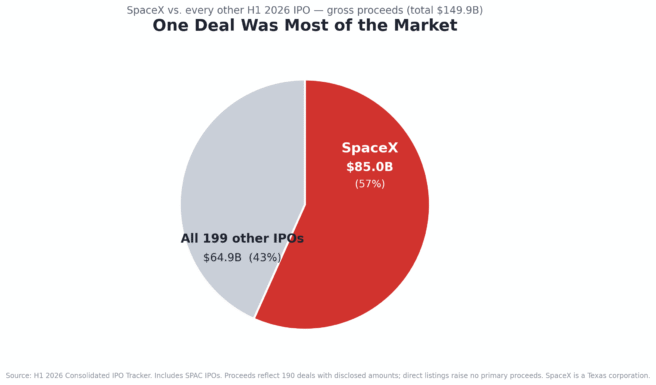
SpaceX Is Big.
SpaceX is just such a huge IPO that I thought it would be interesting to see how the market looked with SpaceX against everything else.
Focus by Jurisdiction
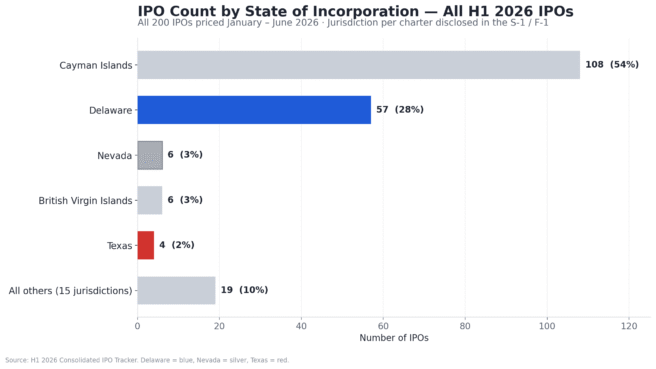
When you look at the overall jurisdictional breakdown in terms of how many companies particular jurisdictions, Delaware picks up just 28% of the market when SPACs are included.
Once you exclude SPACs, the picture looks similar to the total reported for last year by the Delaware Secretary of State’s office. Delaware is coming in at 64%. Nevada and Texas are in the mix.
The Law Firms
Because I have a big spreadsheet and AI to generate infographics easily, let’s look at capital raised by issuers’ counsel and capital raised by underwriters’ counsel. When I first did this, I ran into a SpaceX problem. Basically SpaceX raised so much money that all the other bars are too tightly compressed to show anything. You can see it for yourself. It’s Gibson Dunn’s 2 deals raising 5 times as much capital as Latham’s 13. The SpaceX magnitude just washes out the rest of the bars.
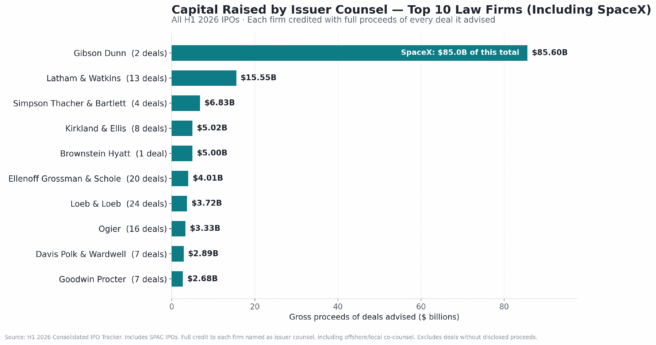
For the next few, I’m just excluding SpaceX.
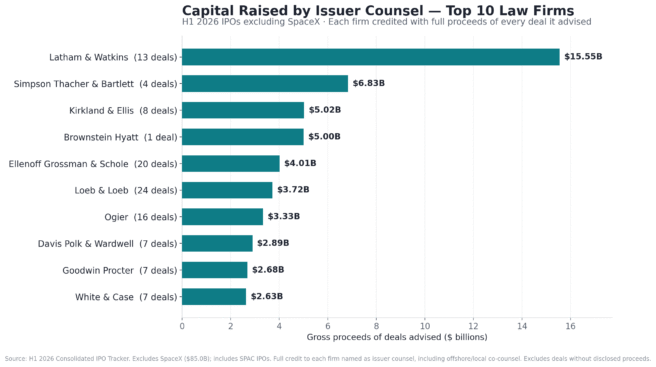
In a few instances, we have multiple firms as issuer counsel. A good example is Brownstein Hyatt with a big Las Vegas office alongside Simpson Thatcher for Pershing Square’s $5 Billion IPO. That $5 Billion is counted for both of them in my chart.
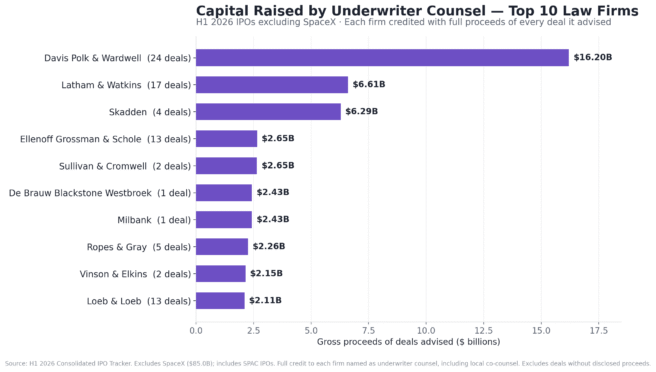
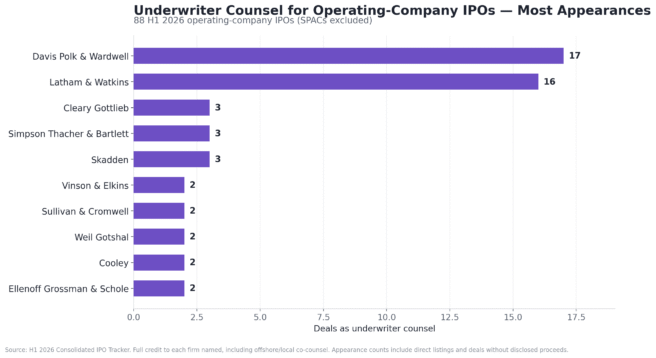
Davis Polk was underwriter’s counsel on SpaceX and still takes the top slot on the underwriter chart even excluding it.
Overall Law Firm Rankings
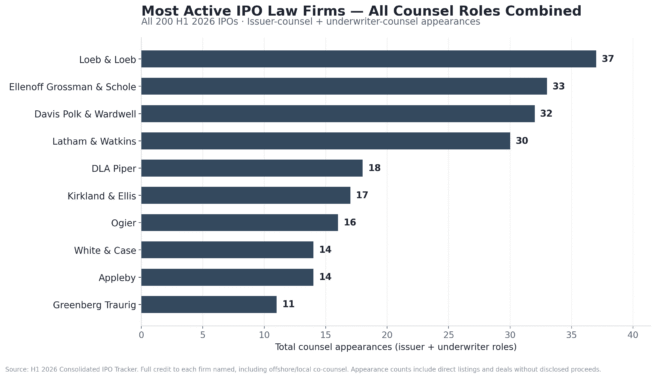
To capture overall activity, this is the top 10 IPO or Direct listing participation for the first half of 2026 as either underwriters’ or issuer’s counsel.
Operating Company IPO Participation – Issuer & Underwriter Representation
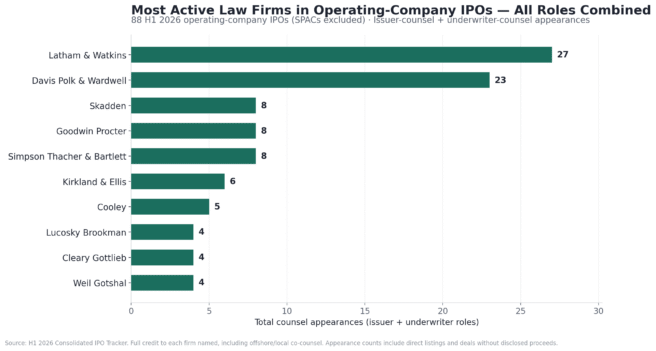
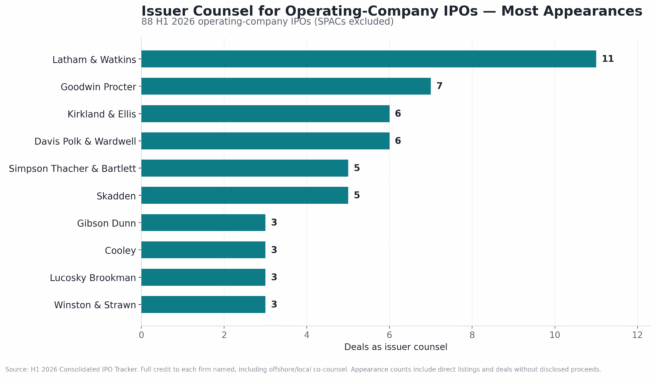
With 88 operating company IPOs, it’s remarkable that Latham was probably involved in about a third of them. Latham and Davis Polk combine for about 60%. Of course, there are probably also deals where they were both involved.
Operating Company IPO Issuer Counsel
Operating Company IPO Underwriter Counsel
SPAC IPO Participation – Issuer & Underwriter Counsel Roles
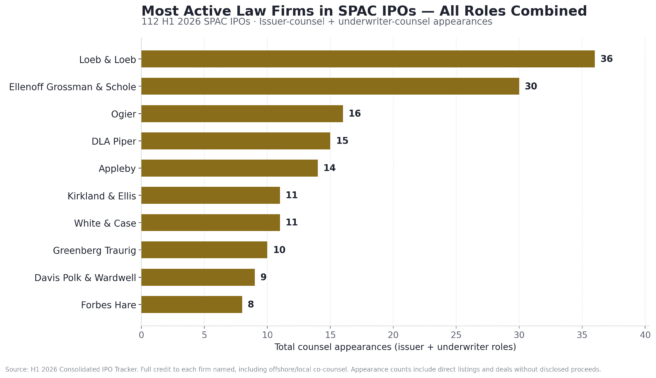
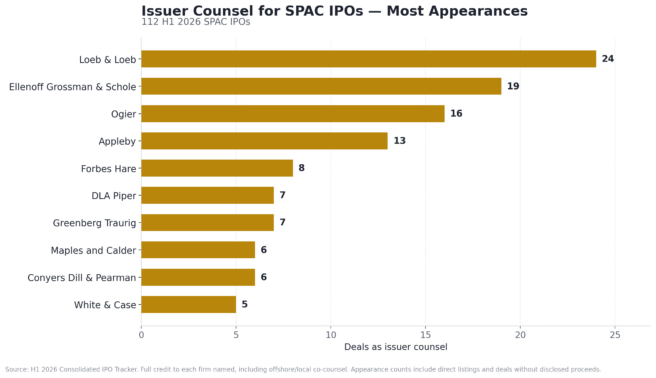
It’s a similar situation on the SPAC side with Loeb & Loeb and Ellenoff Grossman combining for significant presence.
SPAC Issuer Counsel
SPAC Underwriter Counsel
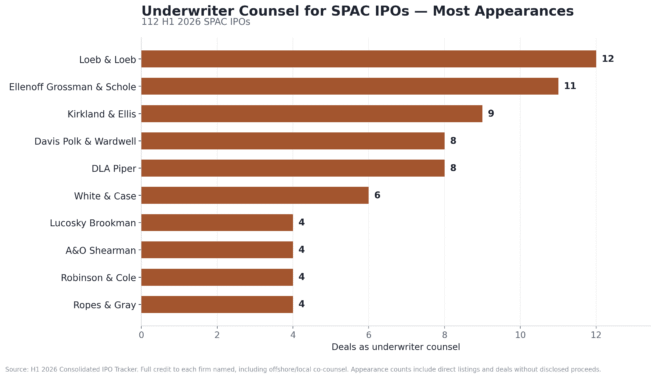
What I take away from these is that there are distinct leaders in operating company IPOs and SPAC IPOs. On the operating company IPO side, Latham and Davis Polk pull away from the pack, doing significantly more deals. On the SPAC side, it’s Loeb & Loeb and Ellenoff Grossman.
Direct Listings
There have also been a significant number of direct listings. I’ll admit that this one surprised me because I expected it to come out the same as IPOs. But Nevada takes this one on a slim margin on deal count.
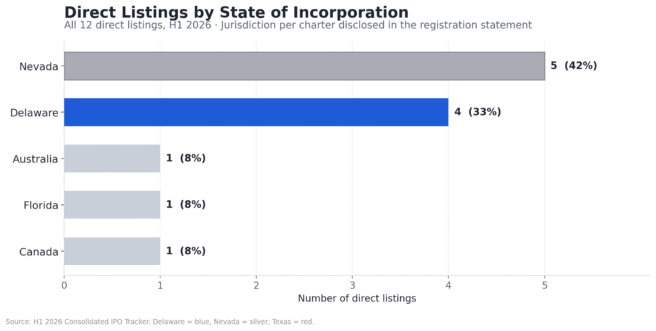
I ran it again by market cap and Delaware’s 4 deals are more than Nevada’s 5 on that front. Nevada drops to third with Australia taking second.
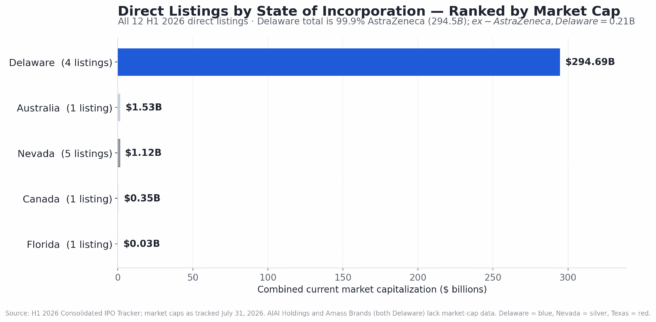
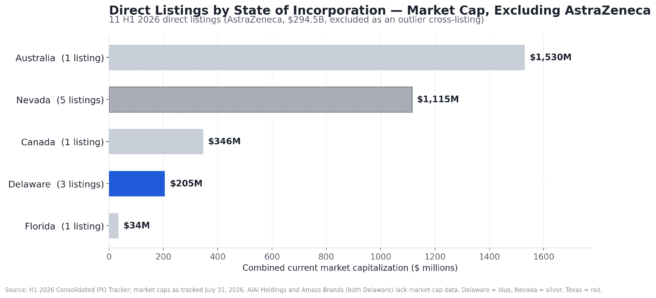
Delaware’s dominance by market cap here is really AstraZeneca driving the magnitude. If you exclude it as we did with SpaceX as a big outlier, the rankings shift and you can actually see the bars again.
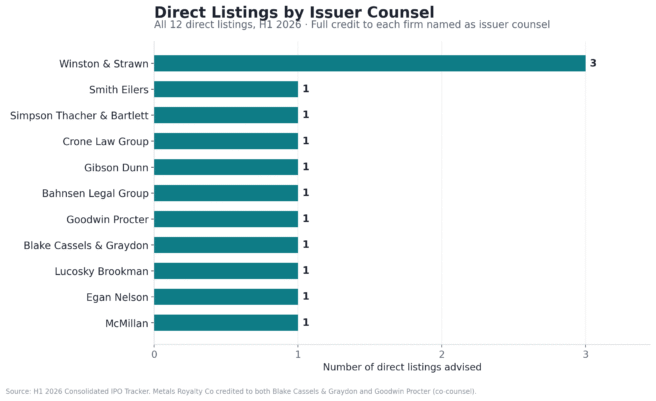
On the direct listing front, let’s not forget the law firms doing the work. It’s a fairly diverse group with Winston & Strawn in the lead.
Underwriter Differences
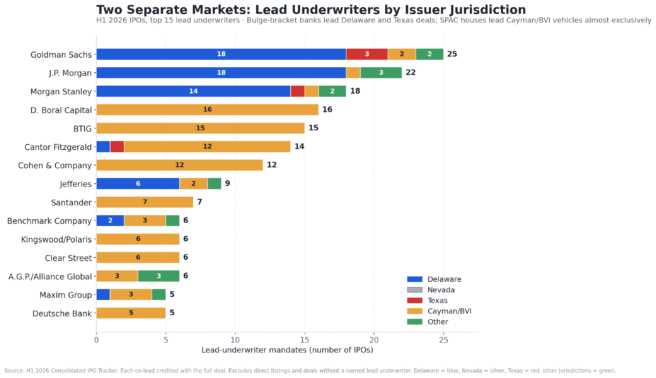
It’s also interesting to look at what’s happening by different underwriters. There are really two different markets with different underwriters. The operating company ecosystem has one set of banks and tends to go to Delaware. The SPACs uses different banks and goes to the Caymans. Here are the top 15 by IPO deal count.
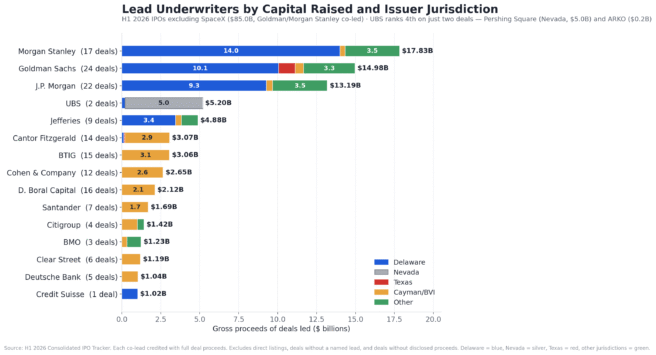
If you look at it by capital raised–excluding SpaceX.
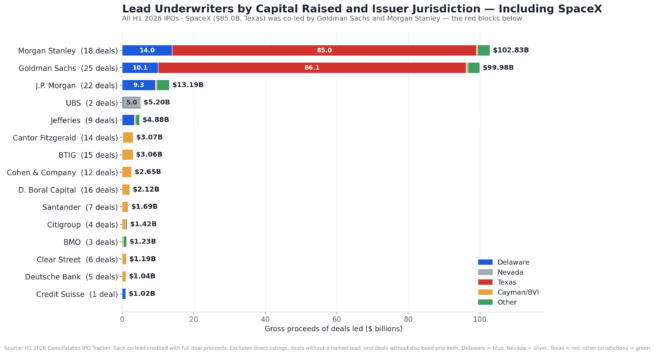
When you put SpaceX in again, its magnitude again flattens everything else out.
Controlled Companies
Different jurisdictions classify companies as “controlled’ under different tests. This looks at companies that identify as controlled companies.
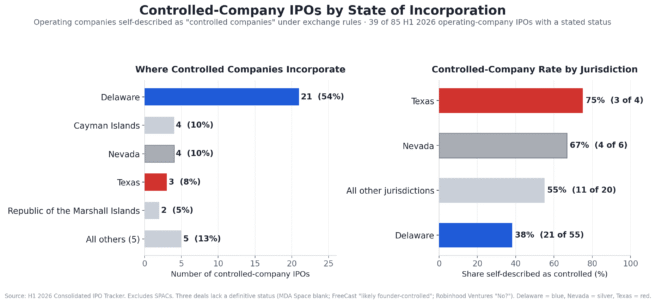
Delaware has the most here in terms of raw numbers. It’s also true that for other jurisdictions, most of what they have picked up comes from controlled companies.
The following chart shows non-controlled companies by state of incorporation.
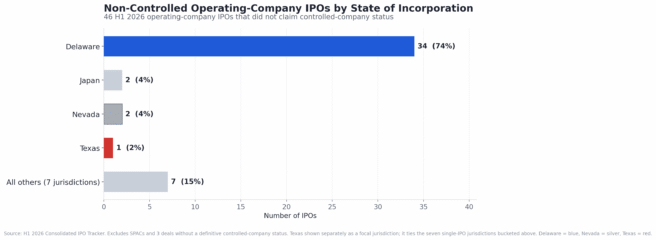
Delaware’s IPO share is down a bit from past years where it used to be over 80% regularly, but,it’s close to the rough range for non-controlled companies.
What I take away from this is that controlled companies are now the ones most likely to pick states other than Delaware. What this market development means is a different question. There are different narratives depending on your perspective. Controlled companies may be more likely to pick alternative jurisdictions because of concerns about Delaware’s litigation environment and a desire to maintain operational flexibility. If you think that Delaware’s litigation environment strikes the right balance now, maybe you read this as controlled companies looking to escape accountability.
Ultimately this is a work in progress and we’ll be spending more time with the spreadsheets to make sure we’ve got it all right and doing more updates. If you think of other things to look at please send an email. I’ll put them in the next update if I can.
Revlon and PBCs
We just got our first decision about directors’ duties in the sale context of a public benefit corporation (PBC); I’m not even aware of any other cases about directors’ PBC duties at all, though I wouldn’t swear there aren’t any.
Honestly at the end of the day it largely comes down to, absent allegations of self-interest, no claims are going to succeed, but let’s unpack the decision anyway, because it raises interesting questions for other contexts.
MPower Financing is a privately-held PBC that issues student loans. Two of its own major lenders held 25% of the company’s stock, and one had rights to designate two board members.
The company was in urgent need of financing, and the lenders proposed to provide it, in exchange for the ability to convert the existing loans into stock, which would result in the lenders owning 85% of the company at a significant discount to the prior round of financing (four years earlier). The other stockholders urged the company to seek a shareholder vote to approve the transaction, and also offered an alternative proposal; the CEO and at least one director agreed the transaction should be subject to stockholder approval. But the board refused, and a special committee – whose disinterestedness was unchallenged, counseled by a financial advisor – approved the deal.
The now-minority stockholders brought a lawsuit alleging that this was, essentially, a Revlon transaction – the board had sold control – and that the board had breached its fiduciary duties in so doing. The board did not dispute that this was Revlon and, by the way, I note that, though there was a dispute among the parties as to whether these were direct or derivative claims, VC Cook analyzed them on the merits without weighing in – so this is an ongoing issue Delaware will have to address eventually.
Originally, the plaintiffs had sought injunctive relief, but after expedition was denied (I assume the deal went through) they apparently were seeking damages.
I should also note that, leaving aside the whole Revlon-PBCness of the dispute, defendants also argued that they were free of liability under DGCL 144(a)(1), which deals with cleansing of conflict transactions. VC Cook, almost as an aside, held that he would have dismissed the claims on these alternative grounds, but also – in footnote 110 – suggested that there was no conflict of interest here, because plaintiffs had not alleged facts to suggest that the lender designees on the board were non-independent. Which raises an interesting question: Does 144(a)(1) cleansing apply outside the context of conflicted transactions? On this, I note that VC David recently dismissed a challenge to a merger, not on DGCL 144(a) grounds, but on Corwin grounds, presumably because no conflict was alleged.
So, you know – awkward.
So, the first issue for VC Cook was whether Revlon is a standard of review or a standard of conduct. As a standard of conduct – that boards must maximize the immediate value of the equity – plaintiffs’ claims would fail right out of the gate, because the board’s fiduciary duty in a PBC is to balance the equity interests against the public interests. VC Cook did not weigh in on the review vs. conduct question (VC Laster has argued, and I agree, it’s review), because he concluded that plaintiffs’ claims failed even if you treated Revlon as a standard of review, and that’s where he devoted the bulk of his analysis.
So, if Revlon is a standard of review, that means you conduct enhanced scrutiny of a decision to sell the company, i.e., a range of reasonableness analysis. But whatever that means in the PBC context, there’s another wrinkle: In the context of a PBC specifically, there is a statutory safe harbor under DGCL 365(b) which provides:
A director of a public benefit corporation shall not, by virtue of the public benefit provisions or § 362(a) of this title, have any duty to any person on account of any interest of such person in the public benefit or public benefits identified in the certificate of incorporation or on account of any interest materially affected by the corporation’s conduct and, with respect to a decision implicating the balance requirement in subsection (a) of this section, will be deemed to satisfy such director’s fiduciary duties to stockholders and the corporation if such director’s decision is both informed and disinterested and not such that no person of ordinary, sound judgment would approve.
So, the question was whether the defendants satisfied the preconditions to this safe harbor with an “informed and disinterested” decision that was “not such that no person of ordinary, sound judgment would approve.”
The “not such” bit reads like a saving for waste claims; VC Cook held there was no waste pled here, which meant, defendants were entitled to the safe harbor if their decision was “informed and disinterested.” Since the plaintiffs did not dispute the disinterestedness of the committee, the relevant question was whether the defendants were “informed.” So that meant, what does “informed” mean in this context?
Here’s where things got interesting. VC Cook noted that in the context of 144 cleansing, there’s a very specific meaning given to informed. That meaning, however, was not included in DGCL 365, and so the common law would control.
A couple of things about this. First, though the situations are not directly comparable, I note that recently VC Will did import DGCL 144’s definitions into a separate question (demand excusal under 23.1). VC Cook did not.
The big issue being, how much do 144 standards migrate to other parts of Delaware law? VC Will held they do, at least in some circumstances; VC Cook held they do not, in the PBC context, and what on earth are we supposed to do with stockholder cleansing under Corwin, which – as I noted above – may or may not evade DGCL 144 when conflicts are not alleged? (This is not totally hypothetical; in addition to VC David’s decision above, see Chancellor McCormick’s Activision decision, which wasn’t decided under the new DGCL 144 but I don’t think that would have made a difference.). Or, stockholder cleansing under MFW, which may still be a thing? Do we have different standards for all these different scenarios, or does the Delaware Supreme Court clean everything up with unified standards? Thanks so much for the certainty, SB 21 drafters!
Anyhoo, VC Cook had to decide what “informed” meant, such that defendants would be entitled to the PBC safe harbor. And that required a decision as to whether the definition of “informed” should shift depending on whether this was a Revlon transaction.
And! He did not weigh in, because he concluded that, either way, plaintiffs had not shown the decision was uninformed. Under business judgment review, I mean, c’mon.
Under enhanced scrutiny review, since PBC directors are required to balance the interests of stockholders against the interests of the public and the specific interest for which the corporation is formed, VC Cook held that plaintiffs would have to show the directors failed to consider all three interests. Op. at 21. But, at best, plaintiffs had only alleged deficiencies with respect to stockholder interests; as the court put it, “this goes only to the stockholders’ pecuniary interests, which is just one of the three interests identified in Section 365(a). Plaintiffs do not allege that the Special Committee failed to take steps to inform itself of the other interests it was required to balance.”
So, not good enough, plaintiffs had not shown the directors’ decision was uninformed, therefore, directors were entitled to the safe harbor of DGCL 365(b).
Without commenting on the specifics of this particular complaint, I think that’s a weird holding. I.e., if directors are required to balance all three interests, it should be sufficient to allege that they failed to inform themselves as to one. Here, however, VC Cook suggested that plaintiffs must allege a deficiency as to all three before a decision would be deemed “uninformed” for the purposes of DGCL 365(b).
Not that it matters when damages are sought because DGCL 365(c) states that, absent a conflict, failure to conduct a balancing of relevant interests is neither disloyal nor bad faith. But apparently, no one argued for the applicability of DGCL 365(c) in this case, so it wasn’t part of the court’s analysis. See Op. at fn. 110.
All of which means, under the most stockholder-plaintiff friendly understanding, absent an uncleansed conflict, and absent a showing of waste, if one is not seeking damages – only injunctive relief (so 102(b)(7) doesn’t apply) – the plaintiff in a PBC case would have to show deficiencies as to consideration of all three interests, apparently, before any kind of breach could be shown entitling the plaintiff to relief.
I don’t expect this to come up a lot in the future, though, so really, the interesting bits are those about how all of these different standards interact with the new DGCL 144/SB 21, and the answer is – so far – ¯\_(ツ)_/¯
And another thing. No new Shareholder Primacy podcast this week as we are on a limited summer schedule, but if you’re that desperate to hear me and Mike Levin, we were recently guests on CII’s Voice of Corporate Governance podcast, available here.
Brooklyn Law Faculty Hiring
Brooklyn Law School seeks applicants to fill three or more full-time, entry-level or lateral tenured or tenure-track faculty positions with an expected start date of July 1, 2027. Brooklyn welcomes candidates with teaching and research interests across all areas of law and especially invites applications from candidates with interests in civil procedure, criminal procedure (investigations), and various areas of business law and contracts, including antitrust, business associations, commercial law, corporate finance, and securities regulation.
Brooklyn Law School, an independent, freestanding law school, is a vibrant intellectual community emphasizing teaching excellence, cutting-edge scholarship, and innovative academic programs designed to prepare students for public service and private practice. Founded in 1901, the law school has a history, tradition, and mission of educating students from a wide range of backgrounds, including underrepresented communities.
Brooklyn Law School is an Equal Opportunity employer and welcomes applicants who can contribute to our mission of fostering a vibrant and diverse community of faculty, students, and staff. All qualified applicants will receive consideration for employment without regard to race, color, religion, sex, sexual orientation, gender identity, national origin, disability, age, or protected veteran status. Salary may range from $145,000 to $250,000, depending on experience, rank, and seniority.
The Appointments Committee will begin reviewing applications on a rolling basis beginning in mid-August 2026. Interested candidates are welcome to apply through the AALS Faculty Appointments Register or by sending a cover letter, C.V., research agenda, and other supporting documents to Professor Alexis Hoag-Fordjour (Chair of the Appointments Committee) at alexis.hoag@brooklaw.edu.
Tulane Law Faculty Search Announcement
Tenure-Track / Tenured Law Positions: Torts and Corporate Law
Tulane University Law School invites applications from entry-level and lateral candidates for
one or more tenure-track faculty positions. We welcome applications from candidates with
teaching and research interests in all topics, but we are particularly interested in candidates
who focus on (1) business and corporate law [at the Assistant, Associate, or Full Professor
rank] and (2) tort law [at the Assistant Professor rank].
To learn more about the law school, visit our website at law.tulane.edu/. Please apply using the Tulane link at tulaneibqejb.fa.ocs.oraclecloud.com/hcmUI/…
All inquiries about the positions should be directed to: Sally Richardson, A.D. Freeman
Professor of Civil Law, Tulane University Law School, richardson@tulane.edu.
About Tulane University
Tulane University is an equal opportunity educator and employer committed to providing
an education and employment environment free of unlawful discrimination, harassment,
and retaliation. Legally protected demographic classifications (such as a person’s race,
color, religion, age, sex, national origin, shared ancestry, disability, genetics, veteran status,
or any other characteristic protected by federal, state, or local laws) are not relied upon as
an eligibility, selection or participation criteria for Tulane’s employment or educational
programs or activities.
Tulane University is responsible for providing reasonable accommodations to individuals
with disabilities throughout the applicant screening process. If you need assistance in
completing an application or during any phase of the interview process, please contact the
Office of Human Resources by phone at 504-865-4748 or by email at hr@tulane.edu.
Quick Followup on the Truth Social thing
After the news broke about Trump Media’s plan to sell access to its data feed, the company offered a line of defense that the feed, though allowing subscribers to trade faster, does not in fact give information to subscribers sooner than it reaches the public:
The White House referred comments to Trump Media. A spokesperson for the company said, “Truth API is designed to deliver posts the instant they are made public to everyone, not before.”
With the caveat that I’m hardly a techie, the theory seems to be subscribers will be able to get their trades in faster because they are plugged directly into the system, even as the post is nominally made available to everyone, and that makes it okay. But let’s take a look at the classic SEC v. Texas Gulf Sulphur Co., 401 F.2d 833 (2d Cir. 1968):
The effective protection of the public from insider exploitation of advance notice of material information requires that the time that an insider places an order, rather than the time of its ultimate execution, be determinative for Rule 10b-5 purposes. Otherwise, insiders would be able to “beat the news,” by requesting in advance that their orders be executed immediately after the dissemination of a major news release but before outsiders could act on the release…. Before insiders may act upon material information, such information must have been effectively disclosed in a manner sufficient to insure its availability to the investing public. …
Coates was absolved by the court below because his telephone order was placed shortly before 10:20 A.M. on April 16, which was after the announcement had been made even though the news could not be considered already a matter of public information. The reading of a news release, which prompted Coates into action, is merely the first step in the process of dissemination required for compliance with the regulatory objective of providing all investors with an equal opportunity to make informed investment judgments. Assuming that the contents of the official release could instantaneously be acted upon, at the minimum Coates should have waited until the news could reasonably have been expected to appear over the media of widest circulation, the Dow Jones broad tape, rather than hastening to insure an advantage to himself and his broker son-in-law.
And here’s the SEC, in In the Matter of Certain Trading In the Common Stock of FABERGE, INC., 1973 WL 150154:
In order to effect a meaningful public disclosure of corporate information, it must be disseminated in a manner calculated to reach the securities market place in general through recognized channels of distribution, and public investors must be afforded a reasonable waiting period to react to the information. Obviously, what constitutes a reasonable waiting period must be dictated by such surrounding circumstances as the form of dissemination and the complexity of the information, i.e., whether it is “readily translatable into investment action” [footnote omitted] … Proper and adequate disclosure of significant corporate developments can only be effected by a public release through the appropriate public media, designed to achieve a broad dissemination to the investing public generally and without favoring any special person or group. To hold otherwise would be to sanction competition for tips in which the ordinary individual investor would inevitably be at a serious disadvantage.
Or more simply:
For purposes of insider trading law, insiders must wait a ‘‘reasonable’’ time after disclosure before trading.
What constitutes a “reasonable” time will vary but since TMTG is literally selling the feed as a way for traders to move before anyone else, I’m pretty sure that’s not it. Do with that what you will.
And another thing. Mike Levin and I talk about the whole mishegoss in more depth on the Shareholder Primacy podcast, and we also discuss new disclosure requirements for (some) activists. Here at Apple; here at Spotify; here at Youtube.
Indiana Maurer Law Faculty Openings
Entry-Level and Lateral Tenured/Tenure-Track Hiring at Indiana University Maurer School of Law
Indiana University Maurer School of Law in Bloomington is seeking outstanding entry-level and lateral tenured/tenure-track applicants to meet needs in a variety of curricular areas caused by planned retirements and University support for expanding the faculty. Curricular needs include AI Law, Business Associations, Constitutional Law and Comparative Constitutional Law, Contracts, Corporate Finance, Cybersecurity Law, Employment Law, Environmental Law, Financial Regulation, Intellectual Property, International Law, International Business Transactions, Law & Technology, Land Use, Property, National Security Law, Real Estate Law, Secured Transactions, and Trusts & Estates. Features of the Maurer School of Law include:
- A highly collegial and productive faculty that is committed to retaining and expanding its community of scholars.
- Integration with a major research university, including cross-disciplinary collaborations with the Kelley School of Business; Hamilton Lugar School of Global and International Studies; Luddy School of Informatics, Computing, and Engineering; Ostrom Workshop in Political Theory and Policy Analysis; and the Paul H. O’Neill School of Public and Environmental Affairs, among others.
- Excellent and ambitious JD, LLM, and SJD students with strong entering credentials.
- A three-course teaching load, small average class sizes, generous support for research conference travel, and an excellent student-faculty ratio.
- Located on one of the nation’s most beautiful campuses in a vibrant Big Ten college town, and home to the world-renowned IU Jacobs School of Music, which presents between 1,100 and 1,400 performances and musical events per year.
Minimum Qualifications include a distinguished academic background and either great promise (for entry-levels) or a record of excellence (for laterals) in both scholarship and teaching, as well as a J.D., Ph.D., or comparable degree.
The candidate will have an expected start date of August 1, 2027. Interested candidates should submit a CV and a letter summarizing their professional experience and future career goals in the areas of scholarship, teaching, and service. Please submit these application materials to https://indiana.peopleadmin.com/postings/33776. Questions regarding the position or application process can be directed to Professor Jennifer Oliva, Chair, Faculty Appointments Committee, at lawappts@iu.edu or by mail to Indiana University Maurer School of Law, 211 S. Indiana Ave., Bloomington, IN 47405.
To be given fullest consideration, applications should be received no later than September 15, 2026; however, the search will remain open until the positions are filled.
Indiana University is an equal opportunity employer and provider of ADA services and prohibits discrimination in hiring. See Indiana University Notice of Non-Discrimination, https://policies.iu.edu/policies/ua-01-non-discrimination/index.html, which includes contact information.
Before a conditional offer of employment with tenure is finalized, candidates will be asked to disclose any pending investigations or previous findings of sexual or professional misconduct. They will also be required to authorize an inquiry by Indiana University Bloomington with all current and former employers along these lines. The relevance of information disclosed or ascertained in the context of this process to a candidate’s eligibility for hire will be evaluated by Indiana University Bloomington on a case-by-case basis. Applicants should be aware, however, that Indiana University Bloomington takes the matters of sexual and professional misconduct very seriously.
St. Mary’s Law Faculty Openings
St. Mary’s University School of Law, the oldest Catholic university in the Southwest and the only law school in San Antonio, Texas, is seeking exceptional candidates for tenured and tenure-track faculty positions to start in the 2027-2028 and 2028-2029 academic years. We are building on our deep history of academic excellence and servant leadership, and we are eager to welcome new members into our vibrant intellectual community.
We are particularly interested in candidates with outstanding academic credentials, successful practice experience, a demonstrated record of scholarly research and publication, and a dedication to teaching excellence. We place great emphasis on fostering a supportive and engaging learning environment, and we are eager to find candidates who excel in the classroom and inspire students to achieve their best.
We are open to passionate and innovative teachers and scholars in all areas, including but not limited to civil procedure, contracts, property, and legal writing. We are hiring one clinical professor in any subject area, with a preference for criminal law specialization.
We do have opportunities for some select Chair appointments for strong lateral candidates in the areas of business law (to include tax), international law, natural resources, and oil and gas. These include the Albert Herrman Professorship in Natural Resources Law; the Turcotte RC Chair in Oil and Gas; the Katherine A. Ryan Chair for Global, Comparative, and International Law; and the James N. Castleberry, Jr. Chair of Oil and Gas Law or Natural Resources Law.
We are also seeking a Director for the Bennie W. Bock II Center for Business and Transactional Law, a new initiative advancing excellence in business law, transactional practice, and responsible AI literacy in service to the greater San Antonio community. We are seeking an experienced, tenured faculty member for this leadership role, though outstanding tenure-track candidates will also be considered.
St. Mary’s University, a Catholic Marianist University, fosters the formation of people in faith and educates leaders for the common good through community, integrated liberal arts and professional education, and academic excellence: www.stmarytx.edu/about. Located in San Antonio, Texas, St. Mary’s is the oldest Catholic university in the Southwest and continues to advocate the Marianist mission. St. Mary’s enrolls approximately 3500 students in a diverse university with four schools, more than 75 academic programs including Ph.D. and J.D. programs, and numerous pre-professional programs. The successful candidate is expected to support and contribute to the University’s Marianist educational mission.
St. Mary’s Law is committed to upholding the Marianist mission. Since our foundation in 1852 by the Society of Mary (Marianists), we have strived to integrate the liberal arts with professional studies, fostering a community where faculty and students alike contribute to a meaningful academic dialogue. We are a Hispanic Serving Institution and are excited to bring cutting-edge teaching and compassionate mentoring to the large percentage of first-generation students that make up our student body.
St. Mary’s Law embraces the AALS Statement on Hiring for Diversity, Equal Opportunity, and Affirmative Action.
If you share our commitment to fostering academic excellence, serving society, and providing exceptional education, we would be delighted to receive your application. Applications can be submitted at stmarytx.applicantpro.com/jobs/4154991. Please submit a letter of interest, CV, and a list of at least three references to Professor Jena Martin, Chair, Faculty Appointments Committee, at lawfacultyhiring@stmarytx.edu. These can also be uploaded to your electronic application. If you are applying for one of the Chairs, please indicate that, and include a statement about how your work advances that specific area of law.
Join us as we continue to advocate for the Marianist mission, shaping the next generation of diverse leaders in law. Your unique perspective and dedication to teaching can contribute significantly to our vibrant and inclusive academic community.
St. Mary’s University is an Equal Opportunity Employer. We look forward to receiving your application.
Charleston Law Faculty Search
Charleston School of Law welcomes applications from entry-level and lateral candidates interested in appointment to full-time, tenure-track positions teaching in the following areas: (1) Constitutional Law; (2) Business Organizations; and (3) Contracts/Sales.
We also invite applications from entry-level and lateral candidates interested in appointment to teach Legal Research, Analysis, and Writing, along with Foundations of Legal Practice.
All candidates must: (1) possess a J.D. or its equivalent; (2) be licensed to practice law in at least one U.S. jurisdiction; (3) have law practice experience; and (4) be committed to exceptional teaching, scholarship, service, and collegiality. Successful applicants must be available to teach in-person during required teaching times beginning with the 2027-2028 academic year.
Charleston Law is an ABA fully-accredited, 501(c)(3) institution that offers a comprehensive three-year program enriched by its longstanding student-centered mission, commitment to an extraordinary classroom experience, and dedication to public service. The campus is located in the Upper King Street district of historic, downtown Charleston, South Carolina, which Travel + Leisure Magazine named as the Number One Best City in the United States for twelve consecutive years from 2013 to 2024 (and ranked as #2 for 2026). The Princeton Review has rated Charleston Law as a top institution for faculty accessibility, teaching quality, and resources for women.
Interested candidates should submit a letter of interest, curriculum vitae, scholarly agenda, teaching evaluations (if available), and reference list to Committee Chair Professor William Janssen at facultyrecruitment@charlestonlaw.edu. Contact Professor Janssen with any questions, at wjanssen@charlestonlaw.edu.
Charleston Law is an Equal Opportunity employer.
Colorado Law is Hiring
We are looking at all levels, with particular needs in Tax, Labor and Employment, and Business, though we welcome applications from all specialties.
Deets: